Methodology Matters
Strategy Construction Methodology
4 Pillars of Methodology
- Signal Generation
- Primary allocation signals generated by machine learning (ML) models trained using factor data, for opportunistic allocation
- Clear delineation of the training, validation and out-sample periods to eliminate overfitting
- Risk Optimization
- Aligns allocation to underlying market price cycles
- Resultant risk reward of at-least 1:3 with a maximum holding period of 30 days, provides guard rails at point of allocation
- Allocation Caps
- Weights allocations to assets are made to respect overall Asset, Sector and Group cap constraints
- Rebalancing caps applied align final allocations to market liquidity, making the strategy executable
- Portfolio Construction
- Each strategy is based on Markowitz model and built by including liquid future contracts
- Independent return streams are reinforced by applying diversification, and allocation across the curve
In summary, AiLA follows a differentiated strategy construction approach to alpha generation with uncorrelated returns
Overview
Background
AILA strategies can be classified into three different types:
- Seasonal Strategies
- Event Driven Strategies
- Trade Flow Strategies
These strategies were then decomposed to see if there is:
- A strong correlation to a particular factor
- Can any single or set of factors explain most of the alpha
- Is the alpha truly a residual which cannot be explained by these 14 factors
Strategies Considered for Analysis
- AILAS002: Euro power & gas strategy
- AILAF010: Diversified commodity strategy
- AILAF012: Event driven diversified Commodity
- AILAS043: Agriculture strategy - Grains, Oilseeds and Softs
- AILAS066: Base metals strategy
Regression Methodology
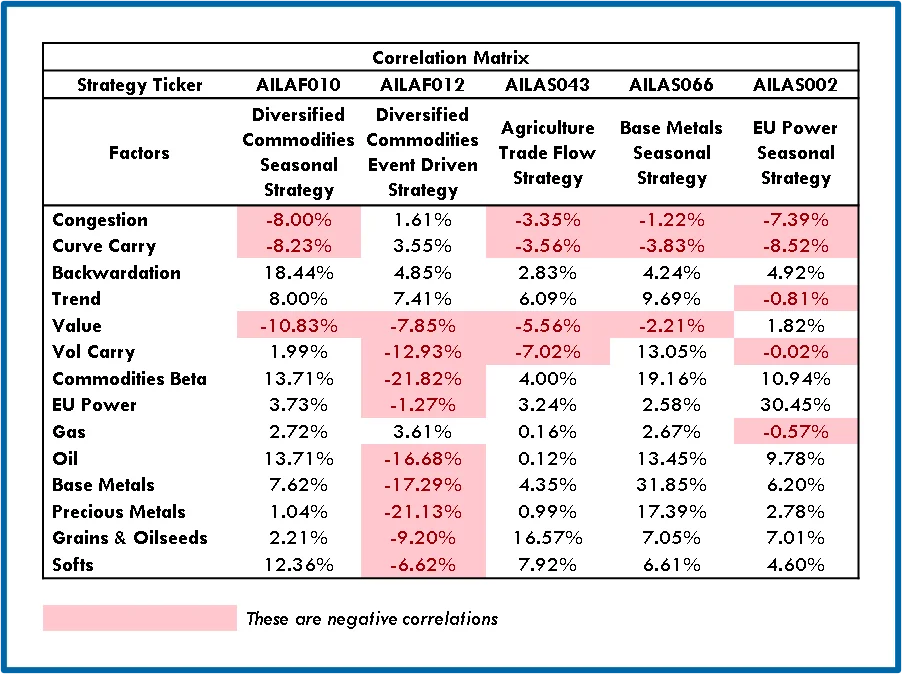
Multivariable regression and correlation analysis of return streams of each strategy with factor returns streams:
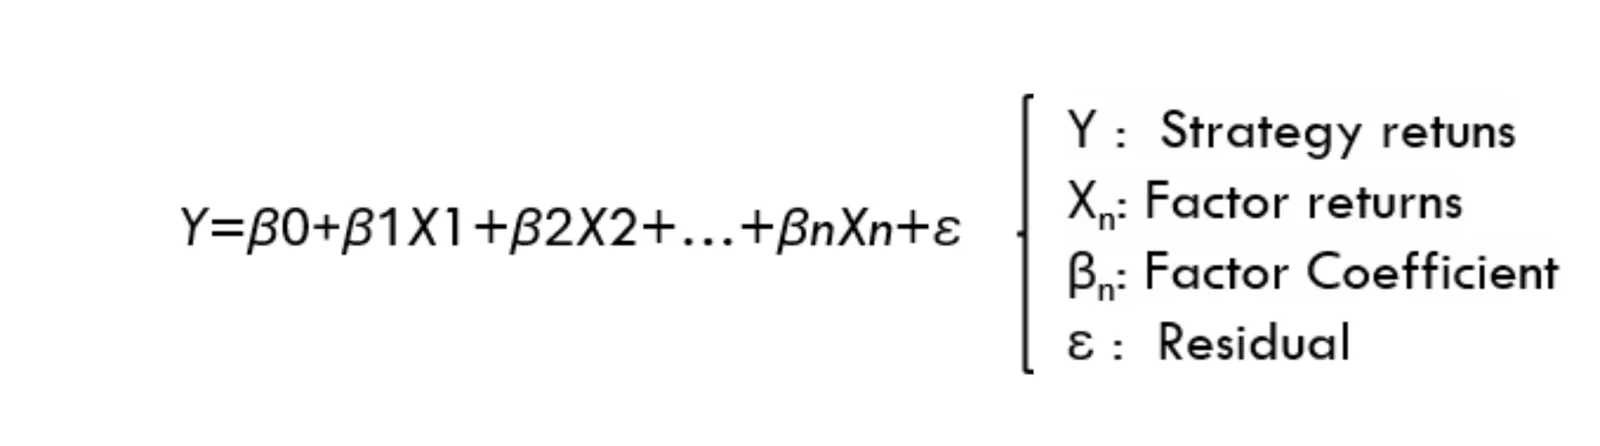
A total of 14 factors were considered in the evaluation:
Standard Factors
- Congestion
- Curve Carry
- Backwardation
- Trend
- Value
- Vol Carry
- Commodities Beta
Sectoral Factors
- Base Metals
- Precious Metals
- Oil
- Grains and Oilseeds
- Soft Agricultural
- Gas
- EU Power
Factor Decomposition
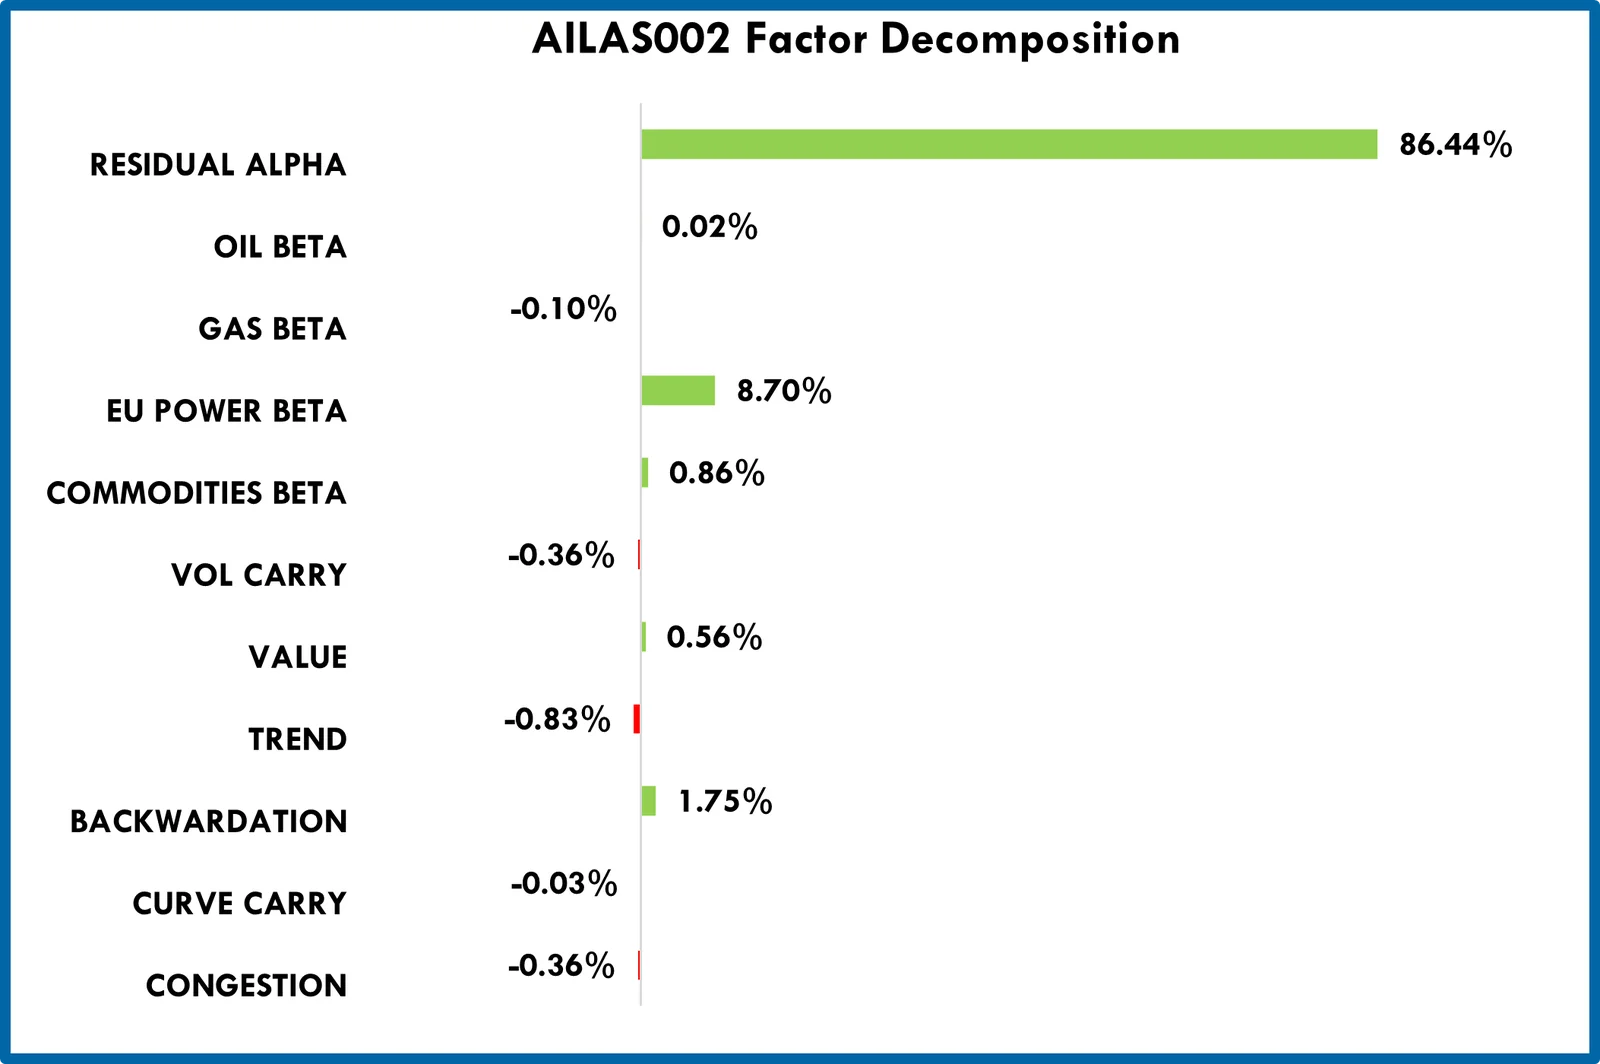
AILAS002
EU Power Seasonal Strategy
- The strategy is uncorrelated to all the 14 factors considered and demonstrates it has a residual alpha which is not explained by the 14 factors considered here
- The key factors which have a statistically significance are Backwardation and EU Power Beta
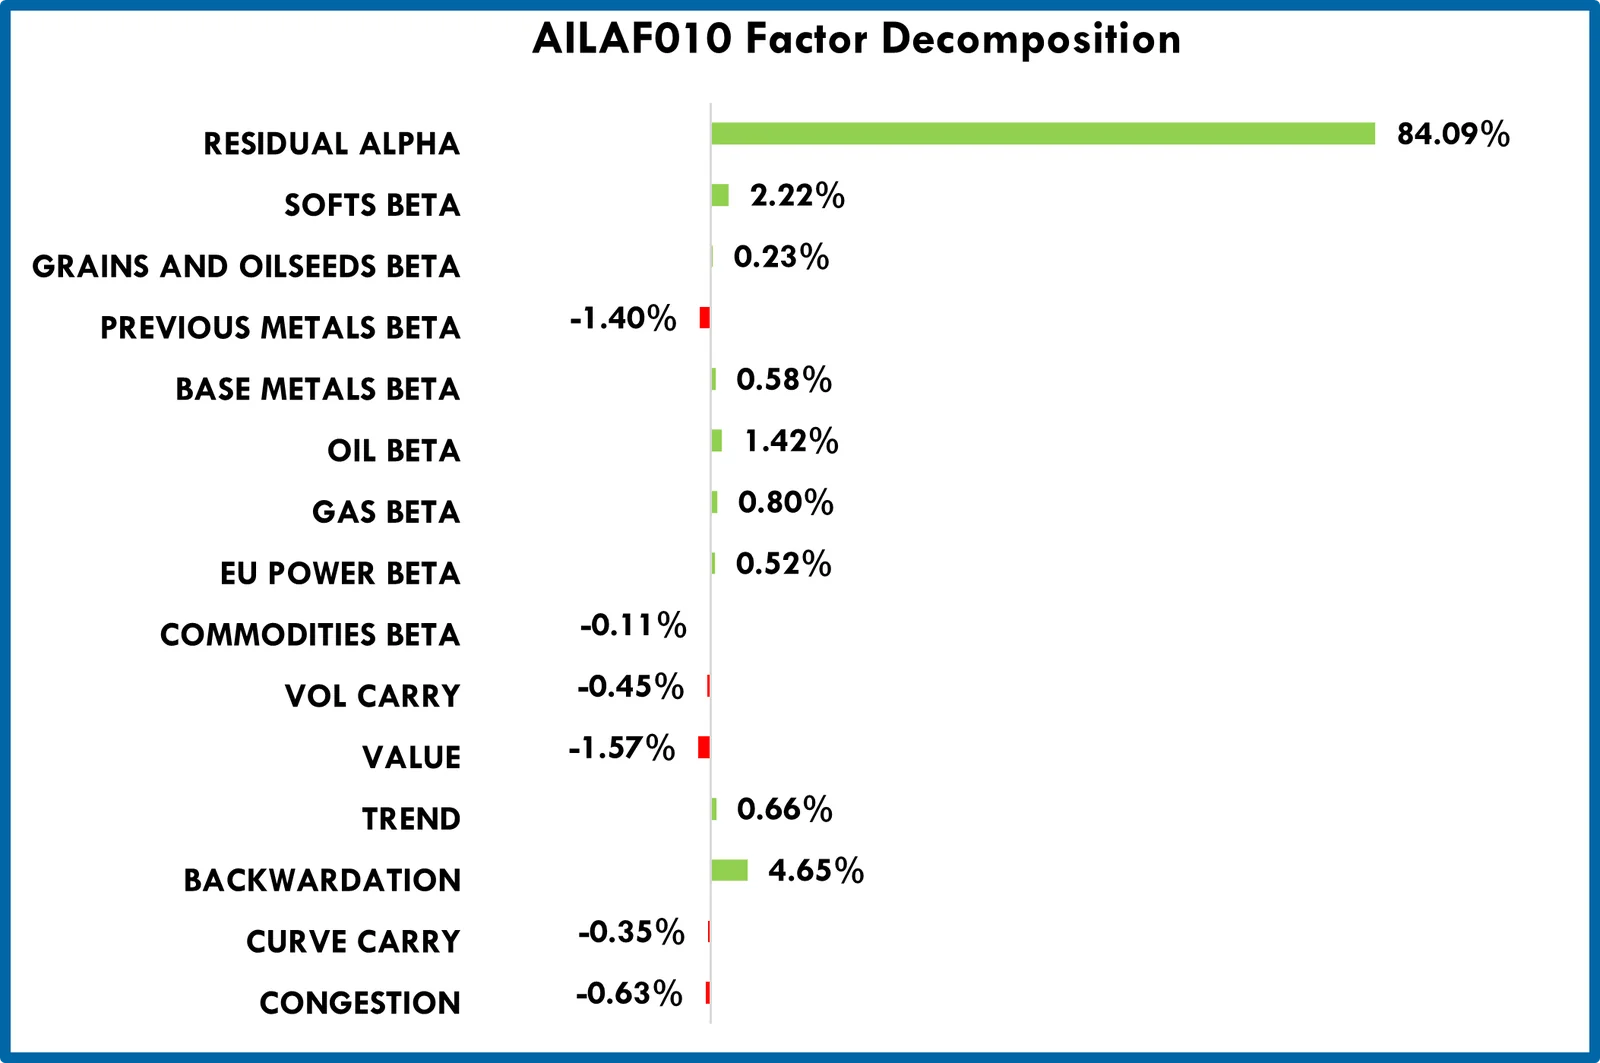
AILAF010
Diversified Commodities Seasonal Strategy
- The strategy is uncorrelated to all the 14 factors considered and demonstrates it has a residual alpha which is not explained by the 14 factors considered here
- The key factors which have a statistically significance are Backwardation, Value, Precious Metals Beta, Softs Beta, and Oil Beta
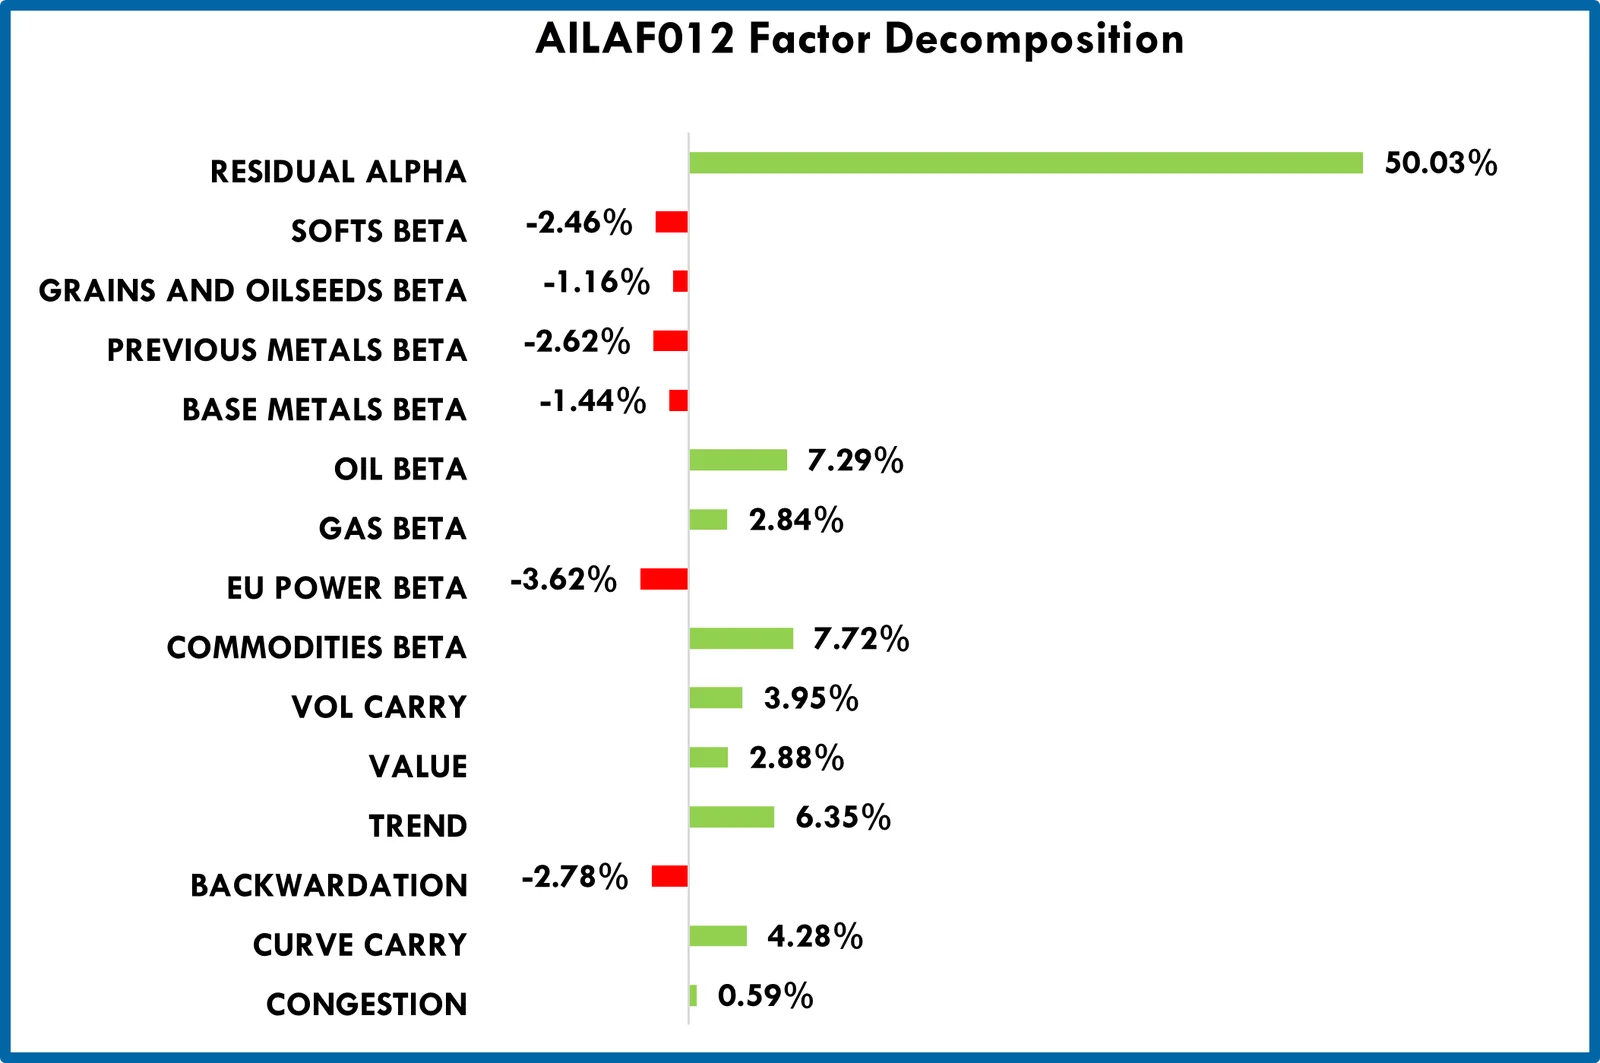
AILAF012
Diversified Commodities Event Driven Strategy
- The strategy is uncorrelated to all the 14 factors considered and demonstrates it has a residual alpha which is not explained by the 14 factors considered here
- The key factors which have a statistically significance are Curve Carry, Trend, Vol Carry, Commodities Beta, EU power Beta, and Oil Beta
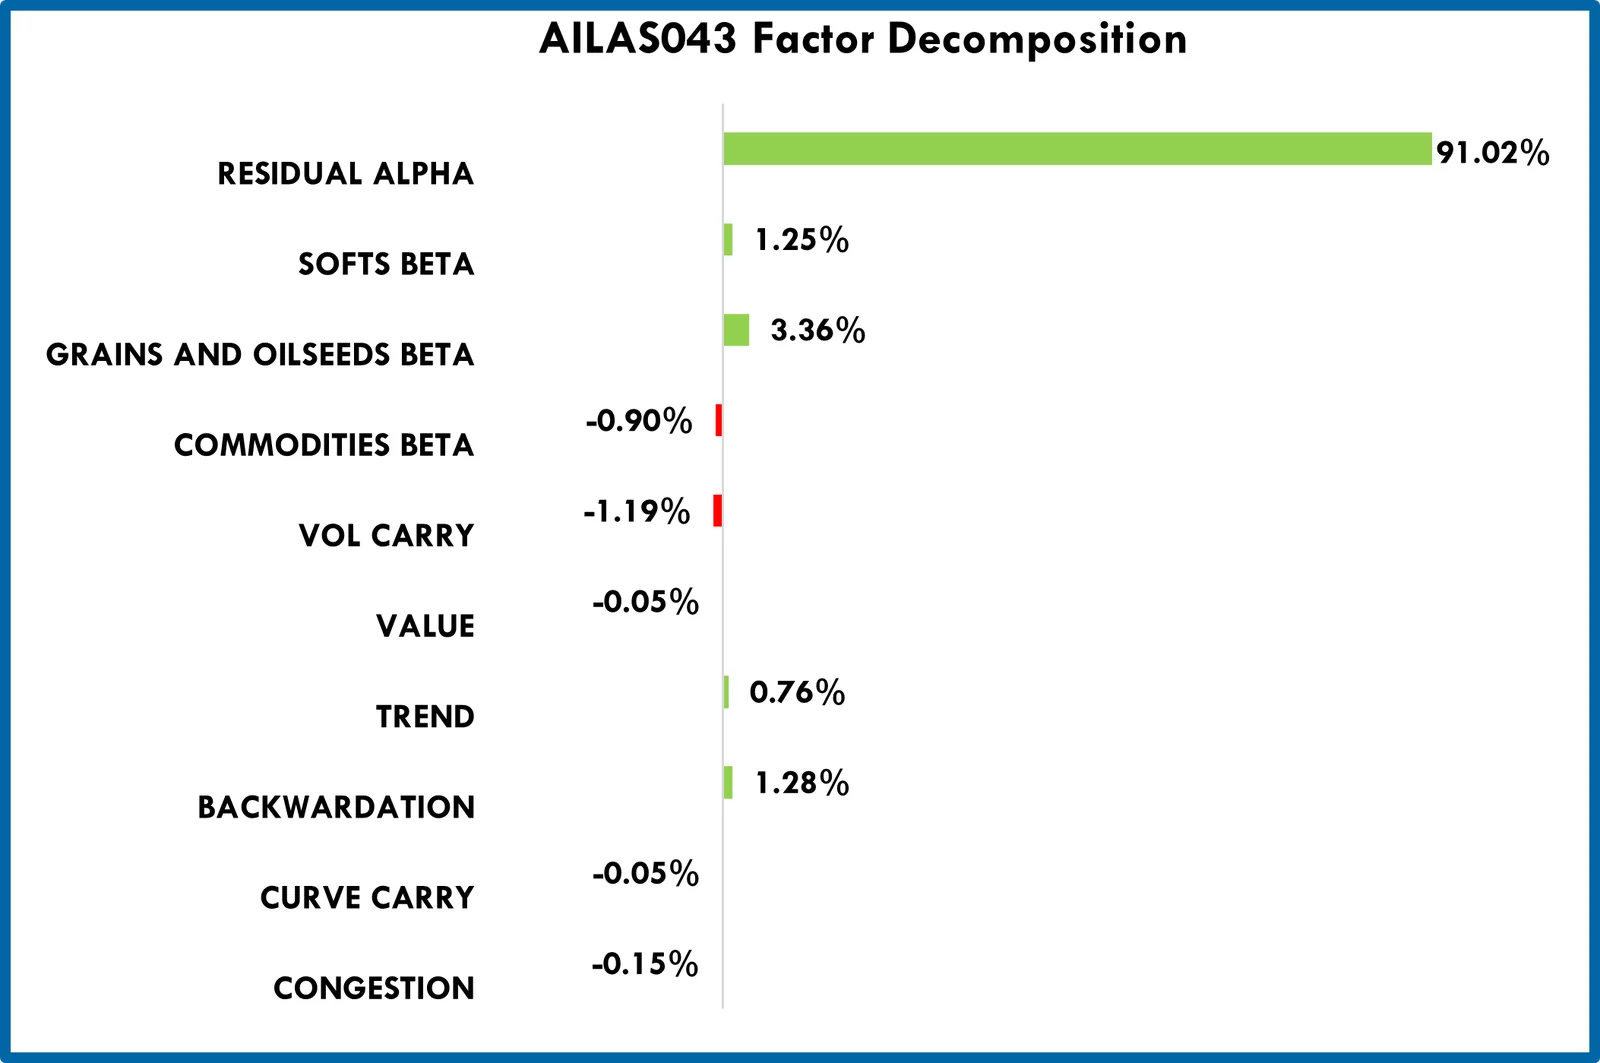
AILAS043
Agriculture Trade Flow Strategy
- The strategy is uncorrelated to all the 14 factors considered and demonstrates it has a residual alpha which is not explained by the 14 factors considered here
- The key factors which have a statistically significance are Backwardation, Vol Carry, Commodities Beta, Softs Beta, and Grains/Oilseeds Beta
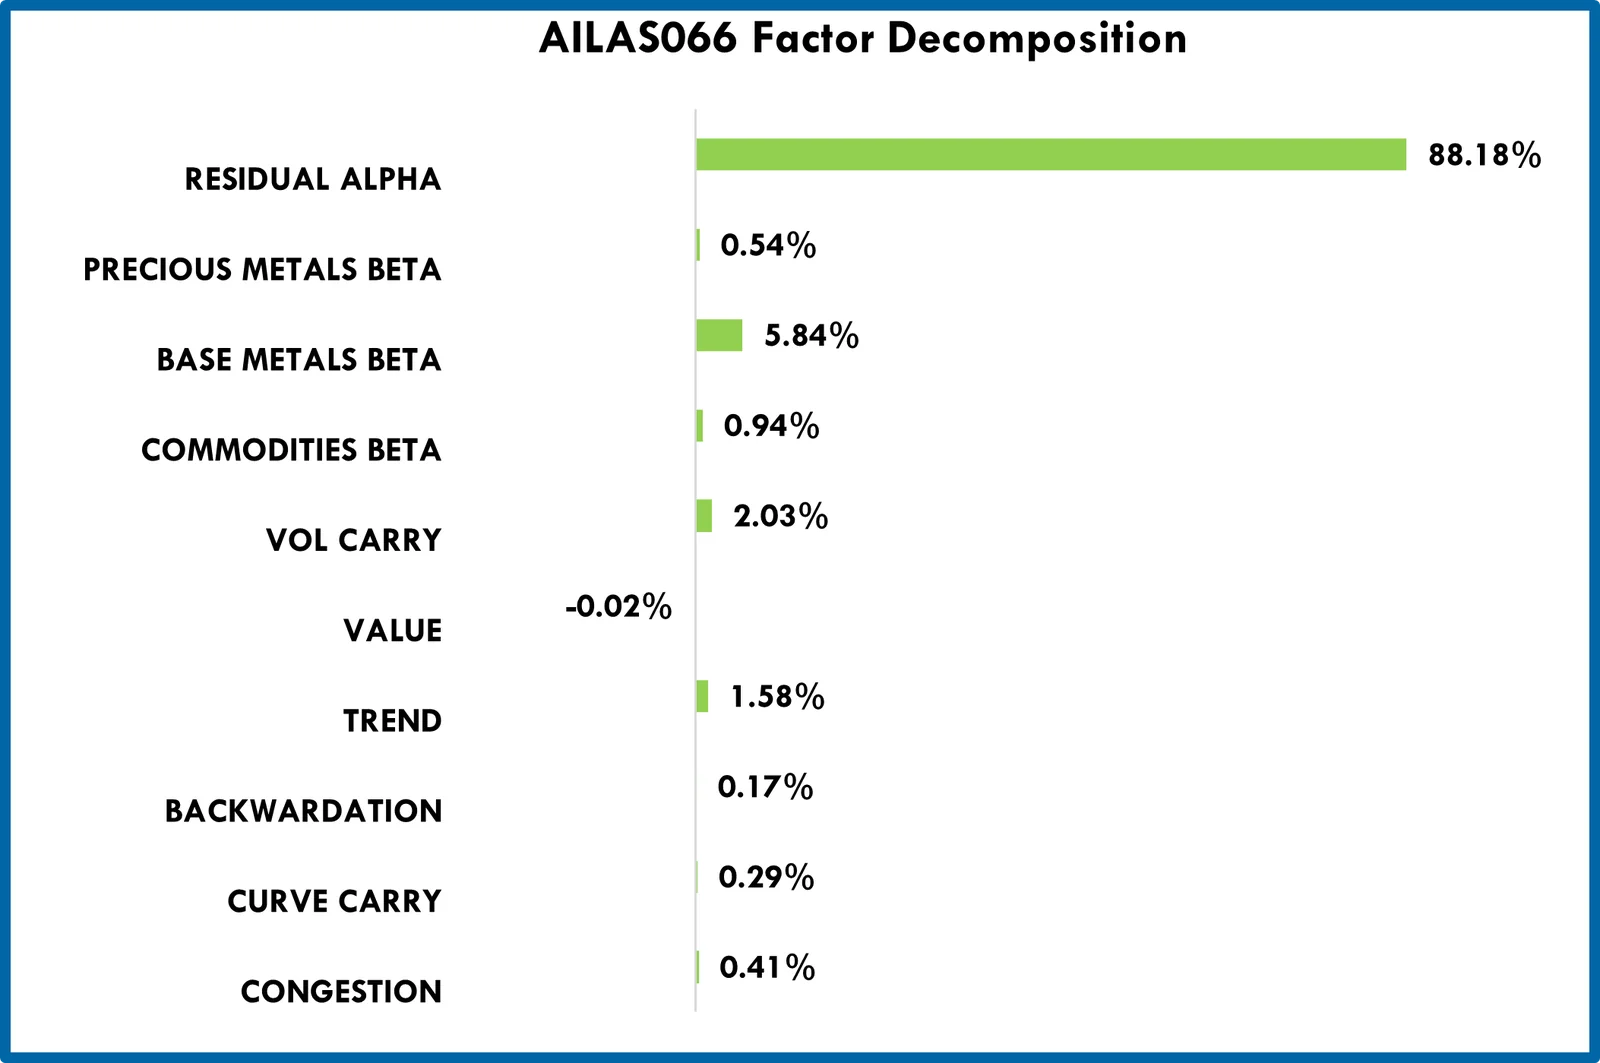
AILAS066
Base Metals Seasonal Strategy
- The strategy is uncorrelated to all the 14 factors considered and demonstrates it has a residual alpha which is not explained by the 14 factors considered here
- The key factors which have a statistically significance are Trend, Vol Carry, and Base Metals Beta
Conclusions
- There is very little correlation between these strategies and standard factors.
- Base metal and Agricultural strategies do show a slightly positive correlation to the respective sectoral factors.
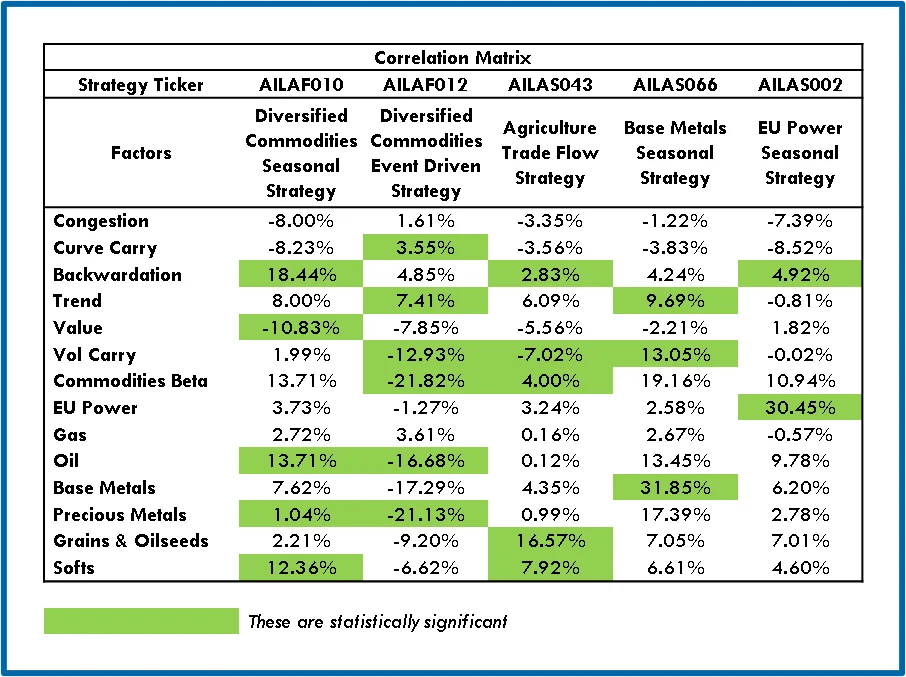
- F012 Strategy as designed has negative correlation to most factors as it's expected to perform when there is a sudden market correction.
- The highlighted factors show which are statistically significant to the underlying strategy.