
Carbon And Commodities Generating Alpha With Dynamically Weighted Index
Negative Asset Prices?
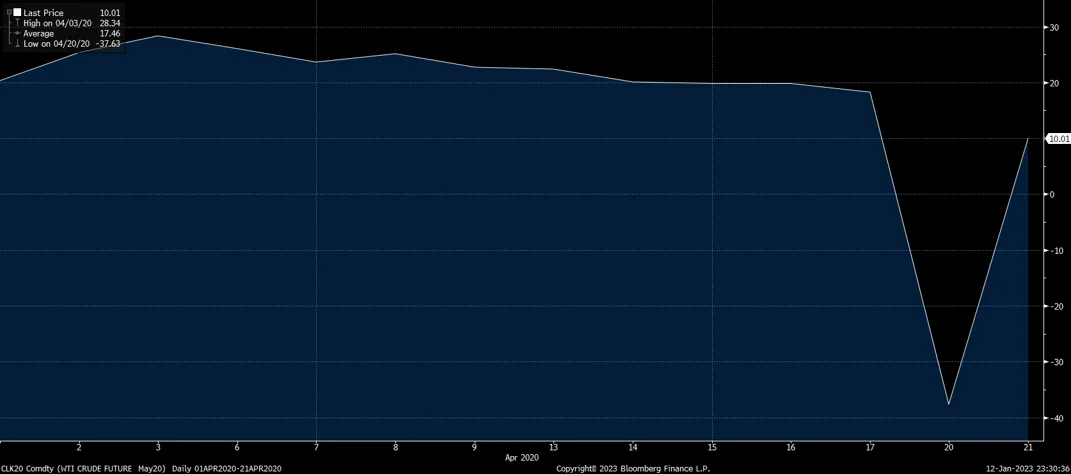
Source: Bloomberg
High Volatility?
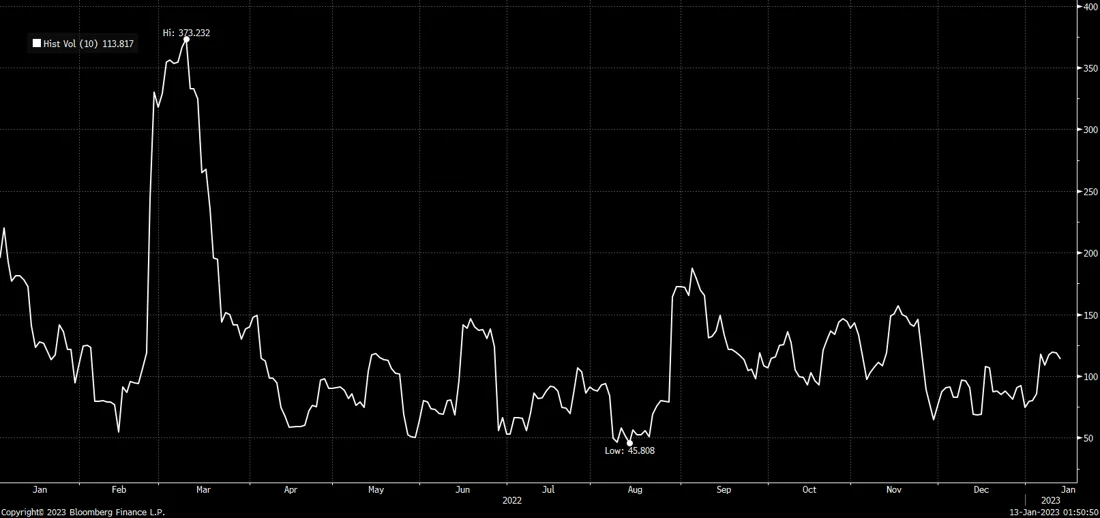
Source: Bloomberg
Relatively Stable Asset Prices?
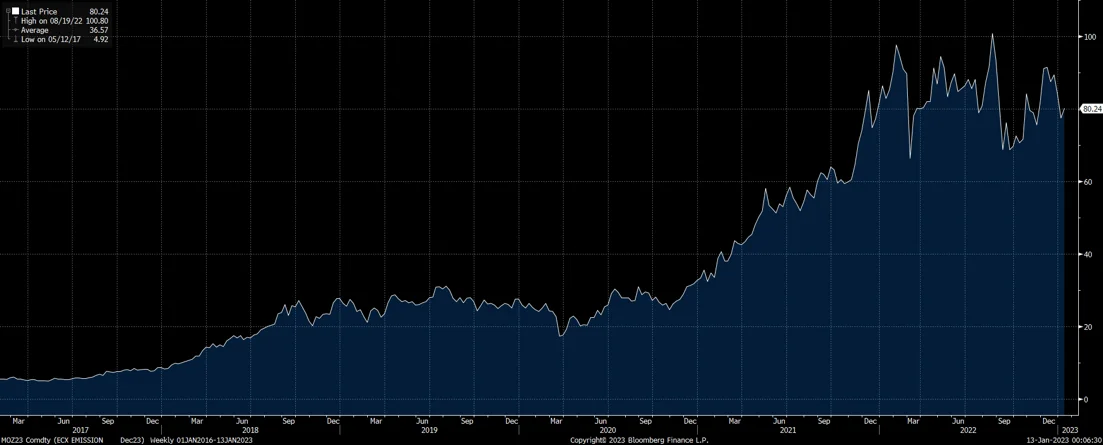
Source: Bloomberg
AiLA Indices
We are a provider of systematic investment strategies in the global Commodities and Carbon market.
Alpha Products | Tracker Products |
| S Series: Low Vol & 1.5 + Sharpe | T Series: Tracking Illiquid Commodities with liquid commodity baskets |
| E Series: Alpha Products in Equity Indices | V Series: Volatility Products in Index Form |
Traditional Commodity Indices
Standard Commodity Indices are typically long-only, fixed weight indices.
Implications:
- Achieves benchmark objective
- Fully allocated – allocations are not opportunistic
- Exposed to cyclical commodity markets in the long term
Table 1 : Example of Fixed Weight Commodity Index Composition
| Group | Commodity | Weight |
|---|---|---|
| Energy | Natural Gas | 8.50% |
| WTI Crude Oil | 15.00% | |
| Grains | Soybeans Gas | 7.50% |
| Corn | 10.00% | |
| Base Metals | Copper | 12.00% |
| Aluminium | 8.00% | |
| Precious Metals | Gold | 14.00% |
| Livestock | Live Cattle | 5.00% |
| Softs | Sugar | 11.00% |
| Coffee | 9.00% |
Standard Commodity Index
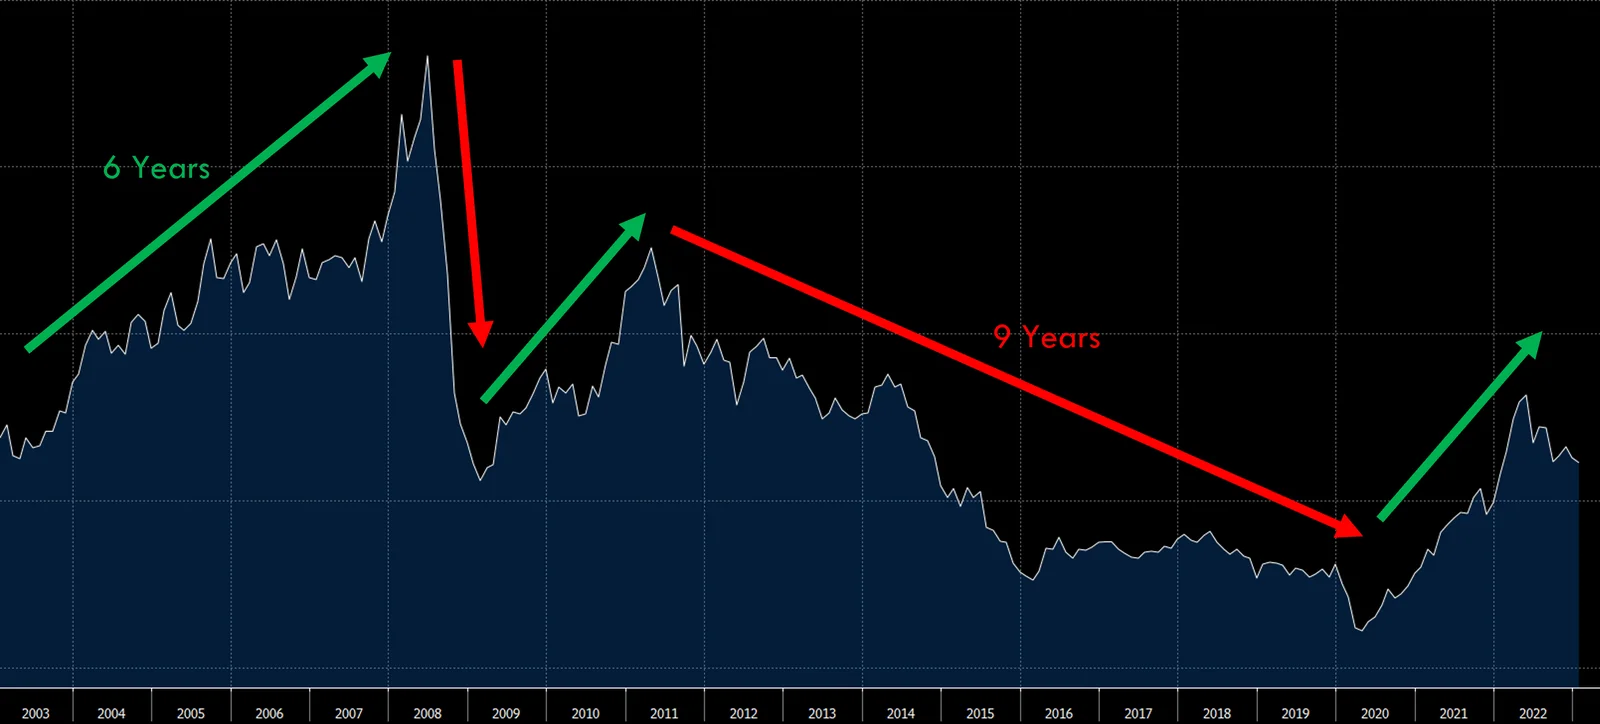
Source: Bloomberg
Dynamic Weights Example – AiLA-S030
Dynamic Weights is part of our DNA in generating Alpha
AiLA-S030 :
Investors can access a Market Neutral Absolute Return strategy focused on diversified global commodity markets.
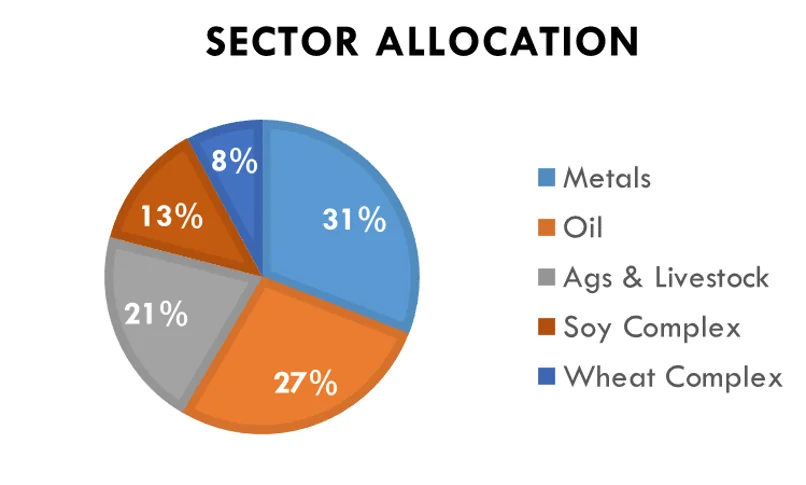
| Metrics* | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 |
|---|---|---|---|---|---|---|---|
| Annual Returns (%) | 15.23 | 12.19 | 14.68 | 22.93 | 27.01 | 12.86 | 1.77 |
| Max Daily Drawdown (%) | -0.72 | -1.84 | -1.96 | -1.85 | -1.68 | -2.42 | -0.26 |
*As of 13th January 2023
Dynamic Weights Example – AiLA-S030
AiLA focuses on Opportunistic Allocation
When to Allocate?
How much to Allocate?
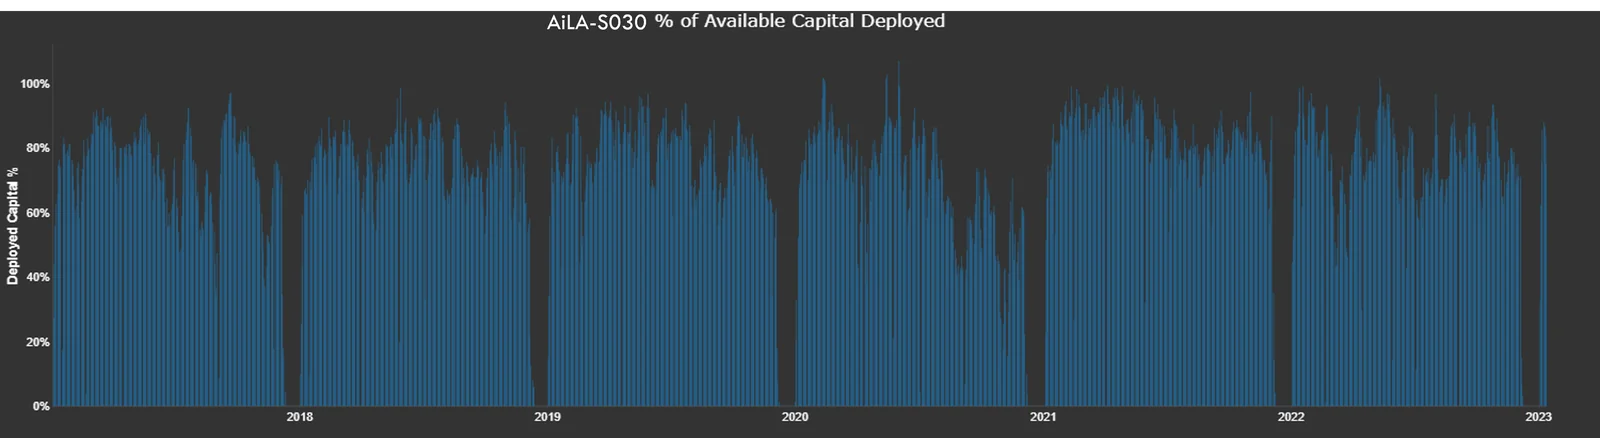
*As of 13th January 2023
Upstream – When to Allocate
1
Are Expected Returns
0% in next 𝑇 +
𝑚 days?
𝑚 can be a window of 30, 45, 60 or 90 days. T is today
2
Is 𝑇 + 1 an ideal time
to initiate a position for
next 𝑚 days?
A decision today can be executed only tomorrow, hence 𝑇 + 1
3
What is the Risk for a
given set of Returns
and Timing?
What if the returns are <0%? Will that be −1% or −5% in the same time horizon of 𝑇 + 𝑚 days
4
Can risk be minimized?
Is it possible to choose a time such that for a given Expected Return and time horizon we have minimum risk
5
What is the ideal time to invest?
If so, is 𝑇 + 1 still the best time to invest or should we wait?
Downstream – How much to Allocate
- Allocation decisions used to generate dynamic index weights.
- Opportunistic nature result in time varying index properties, e.g. allocation, risk and market concentration.
- AiLA follows a common approach (with a few variations) to achieve overall index design targets as well as constraints.
Downstream – Index Construction
| Asset allocation decisions | Construct index representing an ideal composition | Find realistic compromise given targets and constraints | Index allocation weights | Buy CLN3 Flat ClZ3 Sell GCG3 Flat GCJ3 | Unconstrained Index
|  | Constrained Index
| 4% CLN3 0% ClZ3 -6% GCG3 0% GCJ3 |
Dynamic Alpha = Opportunistic ?
- Commodity prices include seasonality as well as other cycles…
- Is the alpha mainly due to “here and now” dynamics…?
- Try to remove allocation timing,
- Create a dynamic AiLA index;
- Convert dynamic index into fixed weights;
- How much of original alpha is explained by fixed version?
Dynamic Index
- Construct dynamic index using AiLA approach.
- Commodity markets typically comprising standard fixed indices.
- Individual long/short futures allocations, with max 12 months to expiry.
AiLA index commodities
- Wheat (CME)
- Corn (CME)
- Soybean (CME)
- Coffee (ICE)
- Sugar (ICE)
- Cocoa (ICE)
- Cottan (ICE)
- Hogs (CME)
- Cattle (CME)
Agriculture
- Crude Oil (CME/ICE)
- Diesel (CME/ICE)
- Gasoline (CME)
- Natural Gas (CME)
- Aluminum (LME)
- Copper (LME/CME)
- Lead (LME)
- Zinc (LME)
- Gold (CME)
- Silver (CME)
Engery
Metal
Dynamic Index
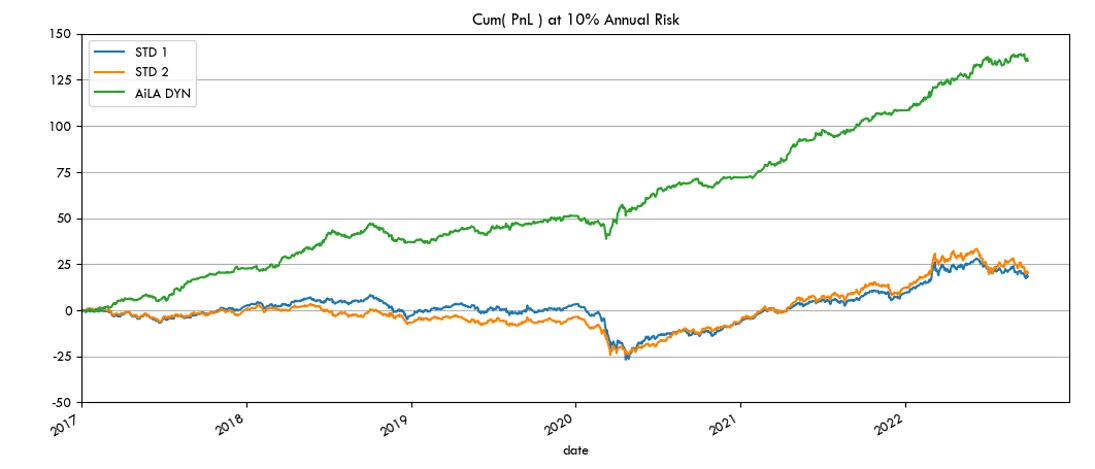
- Many possible contributions to historical difference…
- Perhaps partly explained by a more AiLA like fixed index?
Convert Dynamic to Fixed
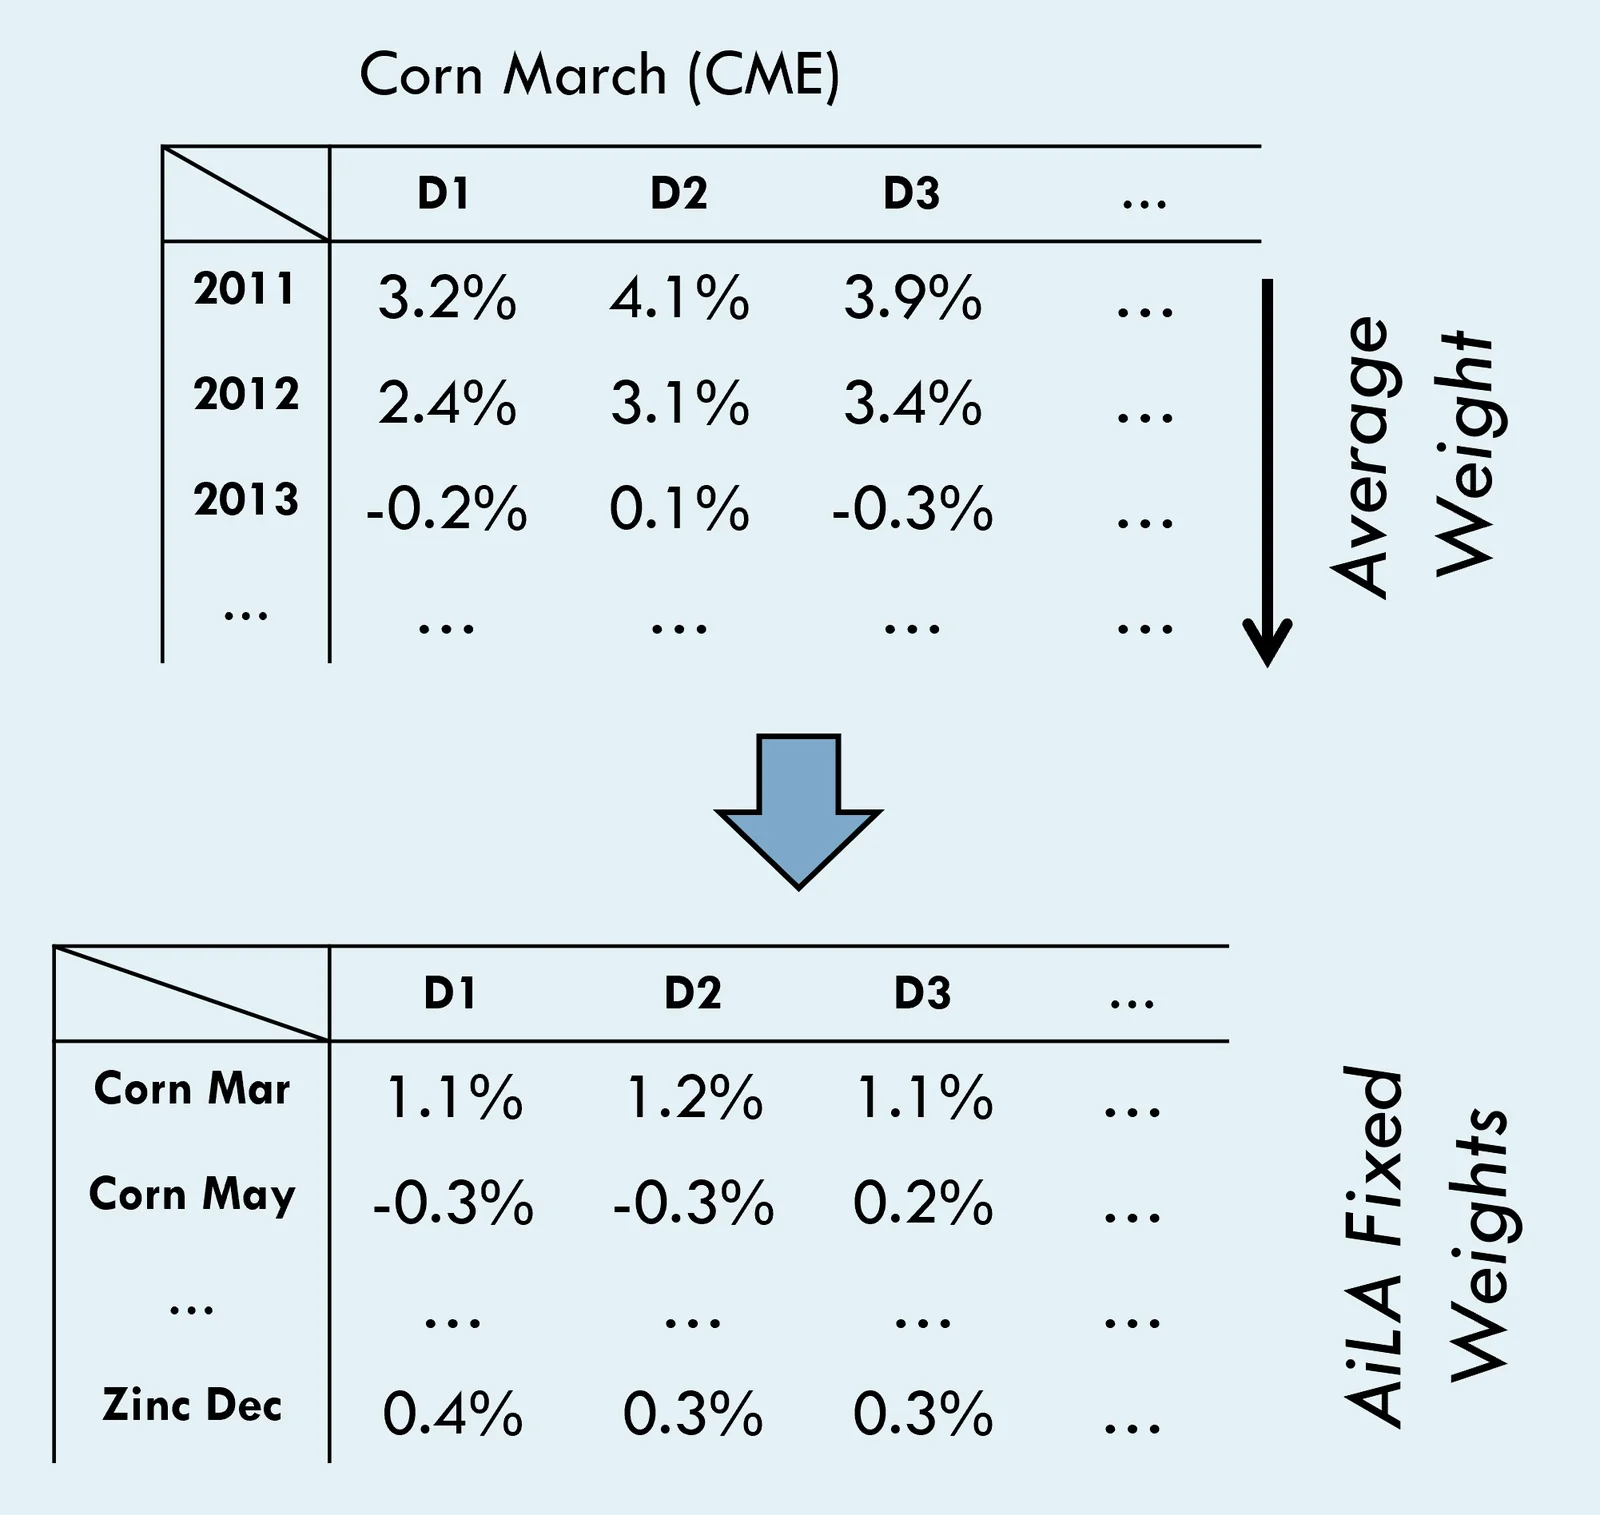
- Fixed weights calculated using period 2011 to 2016.
- Average weights for each day-of-year (D) and asset.
- Scale weights to allocate 100% of capital each day.
- Apply same (fixed) weights each year from 2017.
Convert Dynamic to Fixed
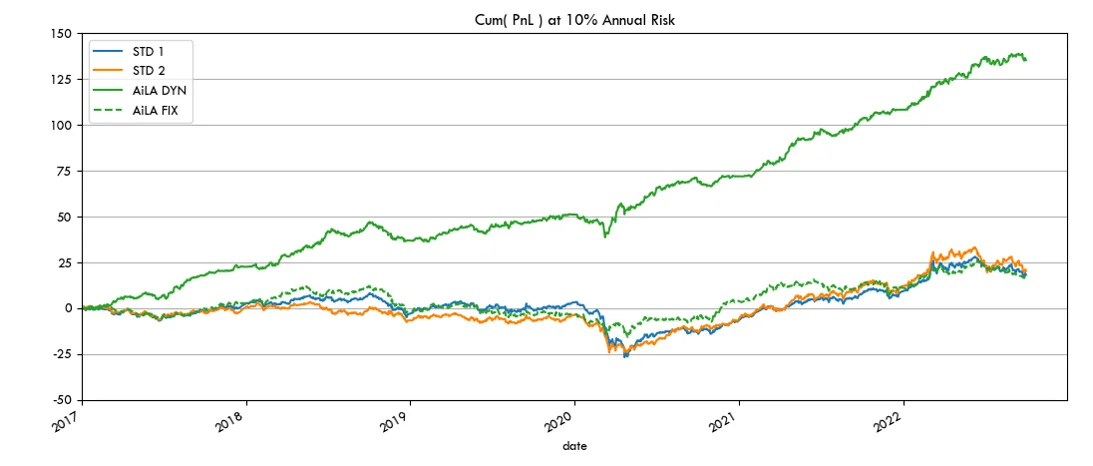
- AiLA version of fixed index similar to standard indices.
- Attribute alpha primarily to opportunistic AiLA weights.
Conclusions
- AiLA is primarily involved in Carbon and Commodity markets, with two types of products – Alpha and Tracker products.
- AiLA aims to generate consistent long term investment alpha, with a different objective from standard fixed weight commodity indices.
- AiLA focuses on opportunistic allocation powered by a systematic process that answers the questions “when” and “how much” to invest.
- The source of AiLA’s alpha originates from opportunistic allocation through dynamic index weights.